Bitcoin Cards Without Altcoin Staking
Short answer: If a card's best rates require staking the provider's token, the real price of the card includes buying and holding that token - cards that reward spending without that requirement compare more honestly.
Some of the highest advertised cashback rates on crypto cards are conditional on staking the provider's own token. That condition changes the product: your yield is no longer from spending - it's from holding an asset chosen by the card issuer. This guide separates the two program shapes and shows how to price the gate.
table of contents
Why staking requirements matter
- The stake is a position. A token bought to unlock a 5% tier can drop 30% while paying you 5% on spending you'd do anyway.
- The position is continuous, not one-off. Wirex documents "no requirement to lock funds to participate" - but the tier tracks the portfolio automatically, and a slip below the threshold downgrades you after a 24-hour grace period [5]. Exiting the position means selling the token, which is exiting the rate.
- The headline hides the cost. "Up to 8% cashback" usually means a low free tier, with the rest priced in a volatile token.
- The reward currency can differ from the gate. Wirex One pays cashback in USD - explicitly "not in crypto, not in tokens" [9] - yet its higher tiers still require a WPAY share of your portfolio. The payout being sane doesn't make the gate free.
The documented tier math
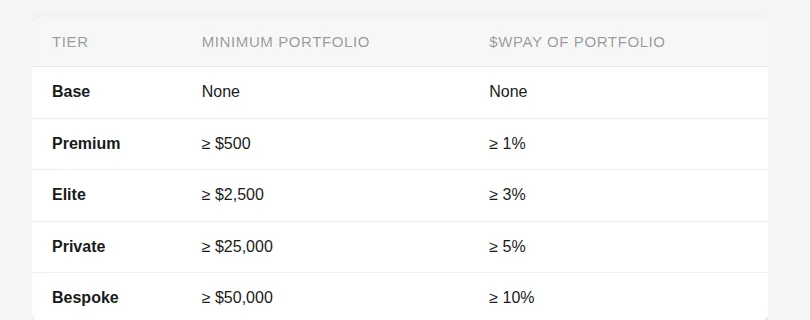
Wirex's own tier documentation is the cleanest example of a decomposed headline. Base tier: 0.50% USD cashback, no conditions [9]. Elite 3.00%: requires $2,500+ portfolio value and at least 3% of it held in WPAY. Private 5.00% and Bespoke 8.00%: $25,000/$50,000 portfolios with 5%/10% WPAY shares [5]. The jump from 0.5% to 3% is priced in a token position you must buy and hold - and its price movement adds to or subtracts from every month's "3%".
Crypto.com's US credit card takes a different route to the same shape: rewards are paid in your choice of BTC or CRO, and the rate ladder is determined by your "Level Up" plan - Basic 1.5% on the first $250/month up to Obsidian/Prime 6% on the first $10,000/month, 2% thereafter [6]. Here the condition is a plan, not a token stake - the same decomposition applies: state the base, price the condition. RedotPay's Pro tier quotes 3% cashback but caps it at $18/month and pays non-withdrawable USD credits [8]. Gate Card advertises up to 8% - paid as points redeemable in USDT or GT, the exchange's own token [8]. In each case the honest rate at zero token/points held is the number to compare first.
Cards that don't need it
These cards pay rewards (or don't pay any) without requiring you to hold the issuer's token:
- Fold (debit and credit): sats rewards on spending, no token stake. The tier lever is a Reserve balance denominated in BTC itself - bitcoin exposure, not altcoin exposure - and boosts are paid in bitcoin after a 30-day pending period [1].
- Freedomia / Goblin / 2Fiat: no rewards program - and no token to buy. The value is the funding model and privacy, not cashback [2][3].
- Xapo: yield comes from your own BTC/USD balances, not from holding a token [4].
Exchange cards (Coinbase, Bybit, OKX) pay rewards in platform credits or selected assets without requiring a token position for the base tier - their cost is the exchange relationship itself, and Coinbase One Card's boost tiers gate on your Assets on Coinbase (a BTC-and-crypto balance, not an issuer token - see the spending-vs-earning guide).
The honest comparison
When comparing cards, normalize for the conditionality:
- Write down the unconditional rate. What do you get at zero token held? (Fold: 0.25% BTC uncapped [1]; Wirex Base: 0.5% USD [5].)
- Price the condition. If unlocking the good rate requires $500 of staked TOKEN, that's $500 at risk. What yield would you need from the cashback difference to justify that risk? (Our cashback calculator computes the break-even spend.)
- Check the exit. How quickly can you leave? Wirex re-evaluates the tier continuously - upgrades apply immediately, downgrades take effect after a 24-hour grace period - so leaving the token means dropping to the base rate [5]. Fold's rewards clear through a 30-day pending period [1]. And check whether rewards accrued before exit survive it.
- Check what the reward is paid in, separately from the gate. USD rewards from a token-gated program (Wirex [5]) are a different product from BTC rewards paid free of gates (Fold [1]) - either half can be the dealbreaker.
When a gated tier can still make sense
If you would hold the token anyway - because you use the exchange, or you want the exposure - the gate is cheaper for you than for someone who would have to buy in. And the tiers occasionally buy real utilities beyond cashback (Wirex's Smart Perks rebates subscription services from Premium up [5]). The discipline is unchanged: value the tier at its conditions, and treat any promised high rate with a stake requirement as marketing until you've priced the token risk yourself.
A worked decomposition
The fastest way to see the structure is to price a real headline end to end. Take a program advertising 8% cashback with a token stake:
- The unconditional base is 0.5% - that is what a new user earns in month one, before buying anything.
- The 8% tier requires a $50,000 portfolio with 10% in the token: $5,000 of position, bought at the market price on the day you unlock the tier.
- The cashback delta between the free tier and the gated tier is 7.5% of your spending. At $1,500/month of spending, that is $112.50/month - a 2.25% monthly return on the $5,000 position if the token price holds.
- Now price the downside the same way. A 30% token drawdown is $1,500 of position loss - thirteen months of the entire delta, gone in one repricing. The break-even question is not "is 8% good?" but "is 7.5% of my spending, net of token risk, better than 0.5% free and clear?"
The same structure explains why BTC-denominated tiers are a different animal: Fold's Reserve gate [1] holds bitcoin, so the position risk is the asset you presumably wanted exposure to anyway. Whether that is a comfort or a doubled exposure is your call - the point of the decomposition is that you make it with the stake's market risk on the table, not hidden behind a cashback headline.
Reading a rewards page critically
Program pages are engineered to blur exactly this line, and four questions cut through most of the blur. What is the reward currency, and is it convertible on your schedule or theirs? What is the unconditional rate, stated as a number rather than "up to"? What position must you hold to reach each tier, and where is that requirement written - the matrix, not the marketing page? And what happens on exit: unstaking period, forfeited rewards, tier downgrade retroactively applied to the month's cashback?
If a program documents all four, you can price it - even if the answer is that the gate is not worth it for you. If it documents none of them, the advertised rate is not a fact, and the safe working assumption is the base tier. That asymmetry - documented programs can be compared, undocumented ones can only be trusted - is the whole reason this guide decomposes headlines instead of ranking them.
Bottom line
If you want bitcoin exposure, prefer cards that pay it in sats or let you hold actual BTC. If you want to avoid altcoin risk entirely, choose a card whose rates don't depend on the issuer's token - our comparison marks which ones do, and the cashback cards ranking shows documented rates side by side.
FAQ
Why is a token-staking requirement a cost?
Because the stake is an asset position you must open to unlock the advertised rate. A token bought to unlock a 5% tier can drop 30% while paying you 5% on spending you'd do anyway - the condition, not the cashback, becomes the main risk.
Which bitcoin cards work without any token?
Fold pays rewards in bitcoin with no token; its tier lever is a Reserve balance in BTC itself. Freedomia, Goblin and 2Fiat run no rewards program and have no token. Xapo's yield comes from your own BTC/USD balances, not a stake.
Wirex advertises up to 8% - what does it really require?
Per its own membership matrix, cashback is paid in USD and the top tiers gate on both portfolio value and a WPAY token share - Elite 3% needs $2,500+ portfolio AND at least 3% of it in WPAY; Private 5% and Bespoke 8% gate on $25,000/$50,000 and 5%/10% WPAY. The "8%" is the top of a ladder priced in a second asset.
How do I compare a gated tier honestly?
Write down the unconditional rate first, then price the condition: if unlocking 5% requires $500 of staked token, ask what return that $500 must earn to beat a flat 1% card at your spending level. The cashback calculator computes the break-even spend.
Is a BTC-collateral tier gate different from an altcoin stake?
Economically similar, asset-wise different. Fold's higher tiers require a Reserve balance of BTC - you take on bitcoin price exposure, not altcoin exposure. If you'd hold BTC anyway, that gate is cheaper than an altcoin stake; if you wouldn't, it's the same trap denominated in a coin you trust more.
Do USD-denominated rewards avoid the problem?
They remove token volatility from the payout but can still gate the rate behind a token. Wirex pays cashback in USD ("not in crypto, not in tokens") yet its higher tiers still require a WPAY share - so check both what the reward is paid in and what unlocks the rate.
Sources
- Fold terms - rewards in bitcoin, no token; tiers scale with a Reserve balance (BTC), 30-day pending period - accessed 2026-10-05
- Freedomia FAQ - no-KYC card, subscription pricing, no token program - accessed 2026-10-05
- Goblin Cards FAQ - no-KYC card, $350 one-time, no token program - accessed 2026-10-05
- Xapo Bank membership - yield on own BTC/USD balances; card spending documented separately - accessed 2026-10-05
- Wirex One Membership - how it works (help center) - tier gates: minimum portfolio value plus WPAY share; "no requirement to lock funds"; downgrades take effect after a 24-hour grace period - accessed 2026-10-05
- Crypto.com US credit card (Comenity) - rewards in BTC or CRO, tier structure via subscription or stake - accessed 2026-10-05
- RedotPay Pro - cashback capped $18/month, USD credits non-withdrawable - accessed 2026-10-05
- Gate Card product page (archive.org snapshot 2026-09-22, live site blocks crawlers) - up to 8% cashback as points redeemable in USDT or GT - accessed 2026-10-05
- Wirex One membership levels & benefits (help center) - cashback rates in USD by tier ("not in crypto, not in tokens"); Smart Perks subscription rebates - accessed 2026-10-05