How Bitcoin Debit Cards Actually Work
Short answer: A bitcoin debit card fronts you fiat at the point of sale and gets repaid by selling your bitcoin. The three variables that matter: when the sale happens, who holds the coins until then, and what the conversion costs you end to end.
A bitcoin debit card is a Visa or Mastercard with a funding mechanism behind it. The merchant sees a normal card payment - every card you can read about here works that way. Everything interesting happens between your wallet and the card network, and that is where the costs, risks and real differences between providers live. This guide walks the full path once, with named cards and current fees at each stage.
table of contents
The path your bitcoin takes
Every bitcoin card runs some version of this flow:
- You fund the card - send BTC on-chain, pay over Lightning, or the app sells BTC from your exchange balance.
- A conversion happens - your BTC becomes USD, EUR, or a stablecoin balance. Or it stays BTC until the next step.
- You pay a merchant - the card network settles in fiat. If the balance was still bitcoin, it gets sold at this moment.
- (Sometimes) you get rewards - some cards pay cashback, a few in actual bitcoin.
Where providers differ is steps 1-3: timing, custody, and price. The rest of this guide is about those three variables - because a card's marketing will not volunteer them.
The three funding models
Direct BTC top-up (on-chain). You send bitcoin to a card address or account. The provider converts it to spending balance either immediately or on each purchase. Freedomia, Goblin Card and 2Fiat work this way. On-chain funding means you pay bitcoin network fees on the way in - on small loads that fee can exceed everything else combined [10].
Lightning top-up. Where supported (Freedomia links a personal Lightning Address to the card), funding is near-instant and the network fee collapses to routing costs - measured by Freedomia's own documentation at roughly 0.25-0.50% through services like Satora or Boltz [7]. This matters most for small, frequent top-ups.
Conversion-only (exchange cards). Coinbase, Bybit, Bitpanda and similar exchange cards never hold your BTC "on the card". They sell it from your exchange wallet and spend the proceeds. Bitpanda states it plainly: your chosen asset "is converted automatically at the point of sale" [5]. Your bitcoin lives on the exchange the whole time; you carry exchange risk plus their conversion fee - 0.9% on Bybit, stacked on top of their own exchange rate [6].
| Card | Monthly | Top-up | FX | BTC sold | KYC |
|---|---|---|---|---|---|
| Fold Bitcoin Debit Card | $0 | 0% | n/d | BTC sold per transaction | Full KYC |
| Freedomia | $5 | 1.3% | 2.5% | BTC sold when you top up | No KYC |
| Goblin Card | $0 | 3.5% | 0% | Not documented | No KYC |
| 2Fiat | $0 | 6.5% | 2.5% | Not documented | No KYC |
| Bybit Card | $0 | 0.9% | 2% | Not documented | Full KYC |
Live values from our database - sources and caveats on each provider page.
When the sale happens - and why it matters
- Sold at top-up: your bitcoin exposure ends when you fund the card. Simple, no volatility, but you've sold even if you never spend it.
- Sold per transaction: you keep price exposure until you actually pay. Coinbase "automatically converts all cryptocurrency to US Dollars for use in purchases" - at the purchase [4]. Bitcoin rising between load and spend works in your favor; a drop works against you.
- Manual sale: you choose when to sell in the app, then spend the fiat. Most control, most effort.
- Not documented: 2Fiat and Goblin Card publish no statement at all about when your BTC is sold [1]. When a provider does not document this, that is itself a finding - you are renting a card from someone who won't tell you what happens to your money.
The sale moment is also the tax moment in most jurisdictions: each conversion is a disposal. Our tax records guide covers what to keep.
Who holds what
On every card that accepts bitcoin, the moment your BTC is converted, your funds are an IOU from the operator (or its custody provider). Fold, for example, runs bitcoin custody through BitGo with the card issued by Sutton Bank [2] - regulated companies, but you are a creditor, not a wallet owner.
The self-custody caveat is worth stating plainly. MetaMask Card and ether.fi Cash market themselves on self-custody, and it is real - funds stay in your wallet until payment. But neither supports bitcoin. MetaMask Card's supported tokens are mUSD, wETH, EURe, GBPe, USDC and USDT [8]. There is, as of our last check, no card that keeps actual bitcoin in your own wallet until the terminal. The closest is a Lightning-funded card, where the coins sit on the operator's balance within seconds of your payment.
The practical rule: a card balance is spending money, not savings. Keep what you plan to spend soon on any custodial product. The self-custody hub covers the alternative for the rest of your stack.
What it costs end to end
The headline fee stack is only part of the cost. The full path, with real documented values:
| Stage | Typical cost | Documented example |
|---|---|---|
| BTC network fee (on-chain load) | $0.02-3, volatile by congestion | 0.2-2 sat/vB in quiet periods [10] |
| Card load/top-up fee | 0-4% | Goblin 3.5%; Freedomia 1.3% (stablecoin deposits) [7] |
| Conversion spread | 0-1.5%, often inside the "0% FX" claim | Bybit 0.9% conversion fee on top of its own sell rate [6] |
| FX fee (non-card-currency spend) | 0-2.5% | Cash App 3% (waivable) [9]; Goblin 0% physical [1] |
| Monthly subscription | $0-10+ | Fold $0 [2]; Freedomia $5 (Founder plan) [7] |
| ATM withdrawal | 0-2% plus fixed, or free tiers | Fold $3.50/withdrawal, $250 max [2] |
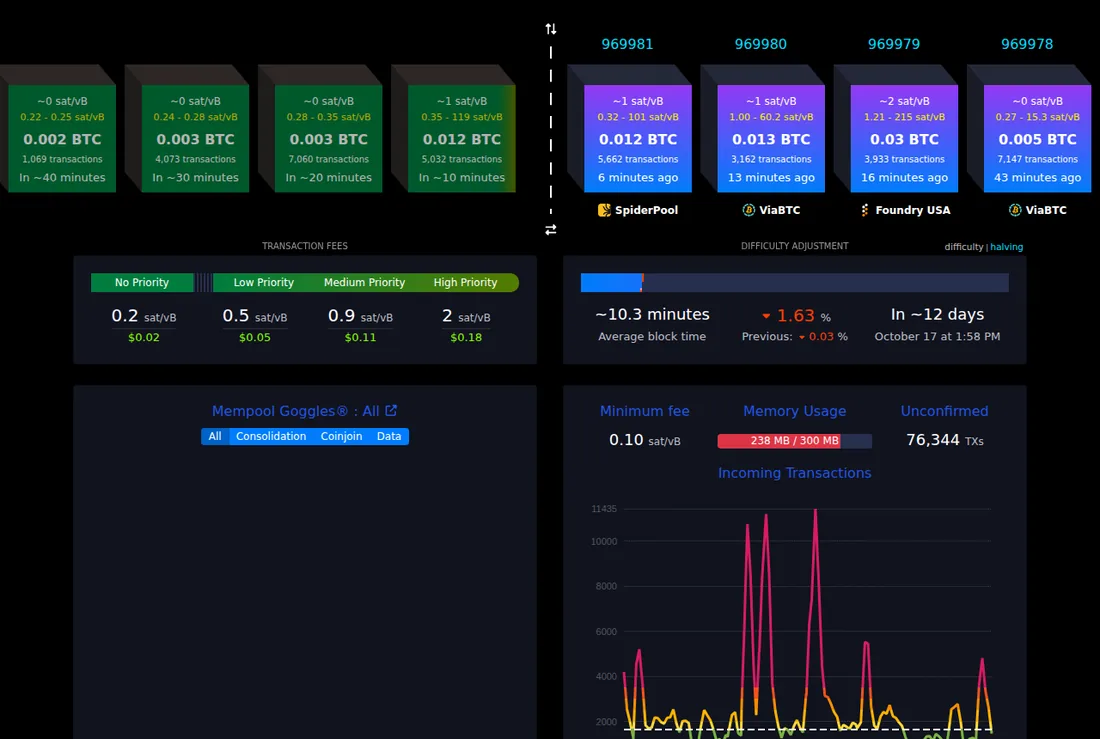
Two things the table hides. First, "0% FX" claims often hide a spread on the conversion rate itself - Goblin's virtual card adds a 1% markup on top of the underlying rate, advertised as a roughly 1.5% total difference from Google rates [1]. Second, network fees swing by orders of magnitude: the same top-up that costs cents today exceeded $3 in past congestion waves [9]. Our hidden spreads guide dissects the conversion markup in detail.
Our fee calculator nets these against your actual spending profile. The cards with the best "0%" headline are not automatically the cheapest at your usage level.
What to do before loading real money
Test the full loop with a small amount: load, pay once, withdraw the remainder. Then check the provider's track record - the dead cards archive exists because programs end, and when they do, the question is only whether you got your balance out first.
Three things worth confirming on the operator's own pages, in this order:
- When is my bitcoin sold? If the site never says, you have learned something important.
- What is the full fee stack - top-up, conversion, FX, monthly, ATM? Not the marketing table, the legal one.
- Who is the issuer, and where are balances held? A named regulated issuer beats an anonymous operator every time - the pre-deposit checklist walks the whole list.
If your funding pattern is small and frequent, the funding rail matters more than any fee line - the on-chain vs Lightning guide compares the two rails directly.
FAQ
Does the merchant receive my bitcoin?
No. The merchant is paid in fiat through the card network. Your operator sells bitcoin somewhere on the way to that payment - the merchant never touches BTC.
When is my bitcoin actually sold?
Depends on the card. Coinbase and Bitpanda convert at the point of sale, Fold converts when you fund the card. Some operators (2Fiat, Goblin Card) never document it - treat that as a finding, not a detail.
Who holds my bitcoin on a bitcoin card?
The operator or its custody partner, from the moment of conversion. A card balance is an unsecured claim on the operator, not your wallet. Keep only spending money on it.
Are there self-custody bitcoin cards?
Not for bitcoin itself. MetaMask Card and ether.fi Cash keep funds in your wallet but support stablecoins and ETH-ecosystem tokens - they do not support BTC. The closest a bitcoin card gets is Lightning funding, where your exposure still sits on the operator's balance.
What does a $100 card payment really cost?
Worked example for a $100 load: network fee $0.05, top-up fee 1.3% ($1.30), FX 2.5% ($2.50) - about $2.85, or 2.9%. The same load on a 0%/0%/0% card costs roughly $0.05. The headline "0%" is not the answer; the stack is.
Do I get rewards in bitcoin?
Some cards pay cashback in bitcoin, most pay it in points or fiat equivalents. Fold's base debit rate is 0.25% in BTC with no reserve required; higher tiers need larger balances. Check our cashback ranking for documented rates.
Sources
- Goblin Card FAQ - order, FX markup, refunds (no sale-timing documentation) - accessed 2026-10-05
- Fold Terms and Conditions - Fold Reserve, 1% BTC buy/sell fee, Sutton Bank issuer, BitGo custody - accessed 2026-10-05
- Fold Cardholder Agreement - $0 monthly, ATM $3.50/$250 max, $3.00 international fee - accessed 2026-10-05
- Coinbase Card (archived product page) - automatic conversion of crypto to USD for purchases - accessed 2026-10-05
- Bitpanda Card - chosen asset converted automatically at the point of sale - accessed 2026-10-05
- Bybit Card fees - 0.9% crypto conversion fee on top of the One-Click Sell rate - accessed 2026-10-05
- Freedomia Help Center - on-chain and Lightning top-ups, 0.25-0.50% Lightning routing, 2.5% FX, $5 Founder plan - accessed 2026-10-05
- MetaMask Card product page - supported tokens are mUSD, wETH, EURe, GBPe, USDC, USDT (no BTC) - accessed 2026-10-05
- Cash App Card agreement (archived) - 3% foreign transaction fee, waiver conditions - accessed 2026-10-05
- mempool.space - live Bitcoin fee and congestion overview - accessed 2026-10-05