Custody, Frozen Accounts and Getting Money Back
Short answer: Custodial card balances are unsecured claims; the realistic protection is small balances, a tested withdrawal loop, records, and picking the strongest custody class - because fiat insurance never covers the bitcoin itself.
The question that matters most on any crypto card is not the cashback rate. It is: what happens to my money when something goes wrong? This guide maps the custody classes, prices what each one actually protects, and walks through what a freeze looks like from the inside.
table of contents
The custody spectrum
Every bitcoin card sits somewhere on a four-step spectrum, and the step decides your legal position - not the marketing.
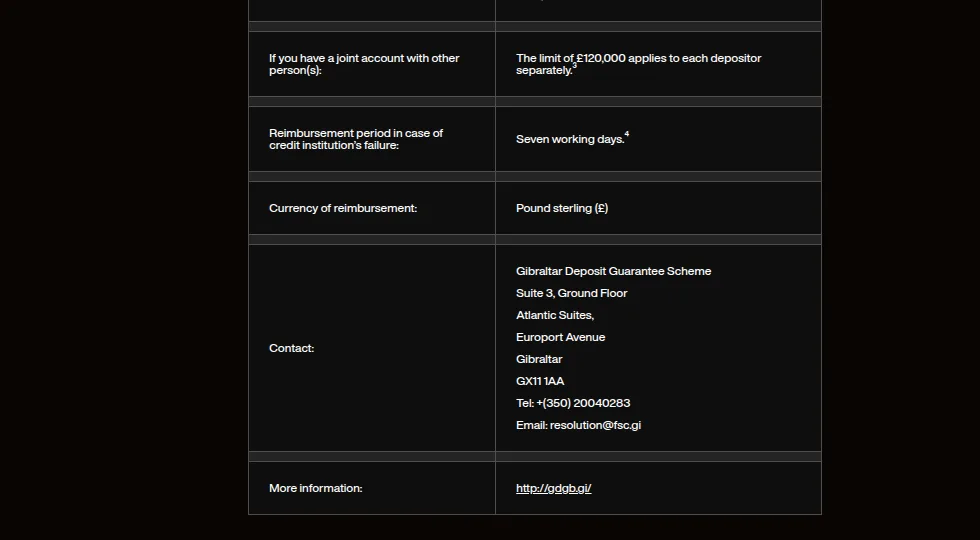
Regulated bank issuer. The fiat balance can be a covered deposit. Two documented examples: Xapo Bank, a Gibraltar credit institution, covers eligible USD deposits under the Gibraltar Deposit Guarantee Scheme - repaid up to £120,000 within seven working days of a failure [1]. Fold's spending account is issued by Lead Bank with FDIC pass-through insurance up to $250,000 per depositor, per insured institution [2]. The critical exception, printed in both documents: crypto balances are not covered. Xapo states crypto asset deposits are not covered by the GDGS [1]; Fold states bitcoin "is not subject to FDIC protections and is not insured by the FDIC" [2].
Regulated EMI / fintech. Many European cards run on an e-money institution. UK-rules EMIs must safeguard client funds - hold them in segregated accounts and reconcile them, per FCA CASS 15 [3]. In an insolvency, safeguarded funds are returned to customers before other creditors. But there is no guarantee scheme and no compensation cap doing the work - the safeguarding is only as good as the operator's bookkeeping. Cryptopay's EU card died this way in 2023 when its issuer's EMI licence was revoked, and cardholders were told to spend or withdraw balances immediately [4].
Exchange balance. Your funds are an unsecured claim on the exchange. Platform risk includes freezes, regional shutdowns, and - historically - operators who stopped returning user funds. Protection is limited to the platform's own dispute process.
No-KYC card operator. Often a barely identified legal entity in an unknown jurisdiction. Goblin's FAQ names "Goblin Solutions LLC" and requires no identity documents for the physical card [8]; Freedomia's FAQ mentions cards "issued from Hong Kong" and names no issuer or regulator at all [10]. No deposit insurance, no safeguarding rules you can verify, no ombudsman. The trade-off for privacy is full counterparty risk - which is a legitimate choice for a small spending balance and a reckless one for savings.
What "frozen" actually looks like
Account freezes happen for: KYC re-verification, AML flags (unusual patterns, crypto-industry payments), court orders, or platform-level risk decisions. The user experience is the same in every case: the card declines, the app says "contact support", and the resolution time is measured in days to weeks.
Community reports across Reddit and Trustpilot follow the same pattern: automated verification loops, support agents who close tickets, and balances stuck for weeks. This is the actual cost of custodial balances - not a hypothetical. The self-custody hub covers the alternative: coins that never sit on someone else's ledger.
The documented failures
Card programs end. When they do, the custody class decides how the story ends:
- TenX, June 2020. Card issuer Wirecard AG collapsed in a EUR 1.9 billion accounting fraud; TenX cards stopped working overnight with the whole Wirecard fleet and never recovered [6].
- Cryptopay, June 2023. EU card issuer UAB PayrNet's EMI licence was revoked by the Bank of Lithuania; cardholders were told to spend or withdraw card balances immediately [4]. The retail program never resumed and closed definitively on 1 January 2026, with remaining balances handled only via manual withdrawal requests [4].
- Trastra, 2025. The Lithuanian operator filed for insolvency in May 2025; a creditor notice followed in August 2025. The site is gone [7].
- Ziglu, 2025. The FCA-supervised firm stopped all payments and crypto activities in June 2025 and entered special administration in July 2025 after its directors concluded the firm was insolvent [5]. Even inside the FCA perimeter, users waited on administrators.
The graveyard documents each case. The pattern: programs with a licensed, regulated issuer and clean separation of client funds returned money; programs with opaque operators often didn't.
The protections that actually work
- Small balances. Keep only what you plan to spend this month. This is the single most effective protection, and the only one that works on every custody class.
- Test the withdrawal loop. Before loading meaningful amounts, withdraw the full test balance back out. A card that cannot return money will not return it when the operator is stressed.
- Prefer the strongest custody class for the fiat leg. A bank-issued card with a guarantee scheme (GDGS [1], FDIC pass-through [2]) legally outclasses safeguarding - and safeguarding beats nothing.
- Know the escalation path. Bank and EMI customers have regulators and ombudsmen [3]; exchange issues run through the platform's process; no-KYC cards have neither.
- Keep records. Export transactions monthly. In a dispute, the burden of proof is on you - our tax records guide explains what to keep.
When to be especially careful
- Provider announces a "migration" or "new BIN partner" - treat as elevated risk until your card works and a withdrawal succeeds.
- Support stops answering publicly (X, Reddit) while the app still works - historically a leading indicator.
- "Maintenance" longer than a few days on the withdrawal function.
- A review finds your operator's licence under regulatory review - move the balance before, not after, the deadline.
A worked freeze scenario
To make the mechanics concrete, imagine the same $600 balance under two different custody classes when a compliance freeze hits on the 1st of the month.
On a bank-issued card, the decline triggers a written ticket. Because the issuer answers to a regulator, there is a defined complaints process with deadlines, and - if the fiat leg sits at the insured bank - the deposit leg is protected up to the scheme limit even in a genuine failure [1][2]. Slow, but bounded.
On a no-KYC card, the same decline leads to a support inbox with no regulator above it. Nothing in the operator's jurisdiction obliges it to answer, publish a wind-down plan, or segregate funds. The balance returns only if the operator remains solvent and willing. That is the entire difference the custody class buys: not faster service, but a legal process instead of goodwill [3].
Both cases share the same practical lesson: the freeze costs nothing if the balance was $60 of grocery money. It costs weeks of stress if the balance was rent. Size the balance for the worst month, not the best.
The bottom line
Deposit insurance and safeguarding never cover the bitcoin on the card - only the fiat leg, and only up to the scheme's limit [1][2]. The four documented failures above all had one thing in common: balances sat on the operator's ledger when the end came. The realistic protection stack is small balances, a tested withdrawal loop, the strongest custody class available to you, and monthly records - in that order.
FAQ
Is my bitcoin covered by FDIC or deposit insurance?
No. Xapo's depositor sheet states crypto asset deposits are not covered by the Gibraltar scheme, and Fold's terms state bitcoin is not insured by the FDIC. Pass-through insurance covers only the fiat deposit held at the insured bank, up to its limit.
What is the difference between a bank issuer and an EMI?
A bank holds your fiat as a deposit that can be covered by a guarantee scheme (Xapo advertises GDGS up to £120,000; Fold's spending account has FDIC pass-through up to $250,000 at Lead Bank). An EMI only safeguards client funds in segregated accounts - protected in insolvency, but no guarantee scheme pays out.
My card suddenly declines and support says "contact support" - what now?
Freeze nothing yet if the balance is unreachable anyway; open one written ticket, ask for the exact compliance reason, and state the balance. Escalate to the regulator or ombudsman only if the operator is regulated - on a no-KYC card there is no escalation path, which is why balance size matters before anything happens.
How much should I keep on a custodial card?
Only what you plan to spend in the near term. Every documented failure - Wirecard 2020, PayrNet 2023, Trastra 2025, Ziglu 2025 - froze balances for weeks to months; small balances turn that from a crisis into an inconvenience.
What is a tested withdrawal loop?
Before loading meaningful amounts, withdraw the full test balance back out to your own wallet or bank once. A card that has demonstrably returned money once is far more likely to return it when the operator is stressed.
Which custody class is strongest?
A licensed credit institution with a deposit guarantee scheme for the fiat balance, followed by regulated EMI safeguarding, then exchange balances. No-KYC operators sit outside every protection framework - the privacy trade-off is full counterparty risk.
Sources
- Xapo Bank Depositor Information Sheet - GDGS covers eligible deposits up to £120,000, 7 working days; crypto deposits excluded - accessed 2026-10-05
- Fold terms of service - FDIC pass-through up to $250,000 per depositor at Lead Bank; bitcoin explicitly not FDIC-insured - accessed 2026-10-05
- FCA Handbook CASS 15 - e-money firms must safeguard client funds in segregated accounts with reconciliations - accessed 2026-10-05
- Cryptopay retail closure notice - retail services ended 1 January 2026; balances via manual withdrawal request - accessed 2026-10-05
- FCA news - Ziglu Limited entered special administration (7 July 2025) after directors concluded insolvency - accessed 2026-10-05
- Wikipedia - Wirecard scandal, EUR 1.9 billion accounting fraud, June 2020 - accessed 2026-10-05
- Cryptowisser card tracker - Trastra insolvency (filed May 2025) and card shutdown timeline - accessed 2026-10-05
- Goblin Cards FAQ - operator "Goblin Solutions LLC", no-KYC physical card - accessed 2026-10-05
- Xapo Bank membership page - Gibraltar-licensed credit institution, GFSC permission, crypto deposits not GDGS-covered - accessed 2026-10-05
- Freedomia FAQ - Hong Kong-issued cards, no issuer or regulator named - accessed 2026-10-05