Bitcoin Cards Abroad - ATMs and DCC
Short answer: Card networks' rates plus the provider's FX fee decide the cost; decline Dynamic Currency Conversion at the terminal and check ATM fees before the trip, because both can exceed 3% per transaction.
Crypto cards spend like any Visa or Mastercard abroad - the merchant sees a normal payment. The interesting costs sit in two places: the conversion chain (FX fee, spread, network rate) and the ATM. Both are avoidable with an hour of preparation. This guide prices both paths with named cards.
table of contents
The conversion chain
Foreign spending with a USD (or EUR) card costs up to three separate things:
- The FX conversion - network rate plus provider markup/spread (see our hidden spread guide).
- The explicit FX fee - 0-2.5% depending on the card.
- The terminal choice - DCC or local currency. DCC is always worse.
The important nuance: even cards that advertise "0% FX" do not convert at exactly the mid-market rate. Bitpanda's card page says "0% FX fees — For non Euro transactions (VISA mark-up fees apply)" [3] - the network's own margin stays in the rate. The strongest travel options are the cards with 0% own-FX and documented network-rate conversion (Bitpanda in the EUR area, Xapo worldwide), because the remaining cost is one known margin instead of two unknowns.
ATM withdrawals abroad
Crypto cards vary more on ATMs than fiat cards:
- Percentage fee - typically 2% (Xapo: $100/month free, then 2%, $2,000 daily limit [4]).
- Fixed fee - $2-5 per withdrawal, punishing small draws.
- Daily/monthly limits - lower than bank cards on several crypto products.
- Local operator fees - independent of the card, charged by the ATM owner, often $2-5.
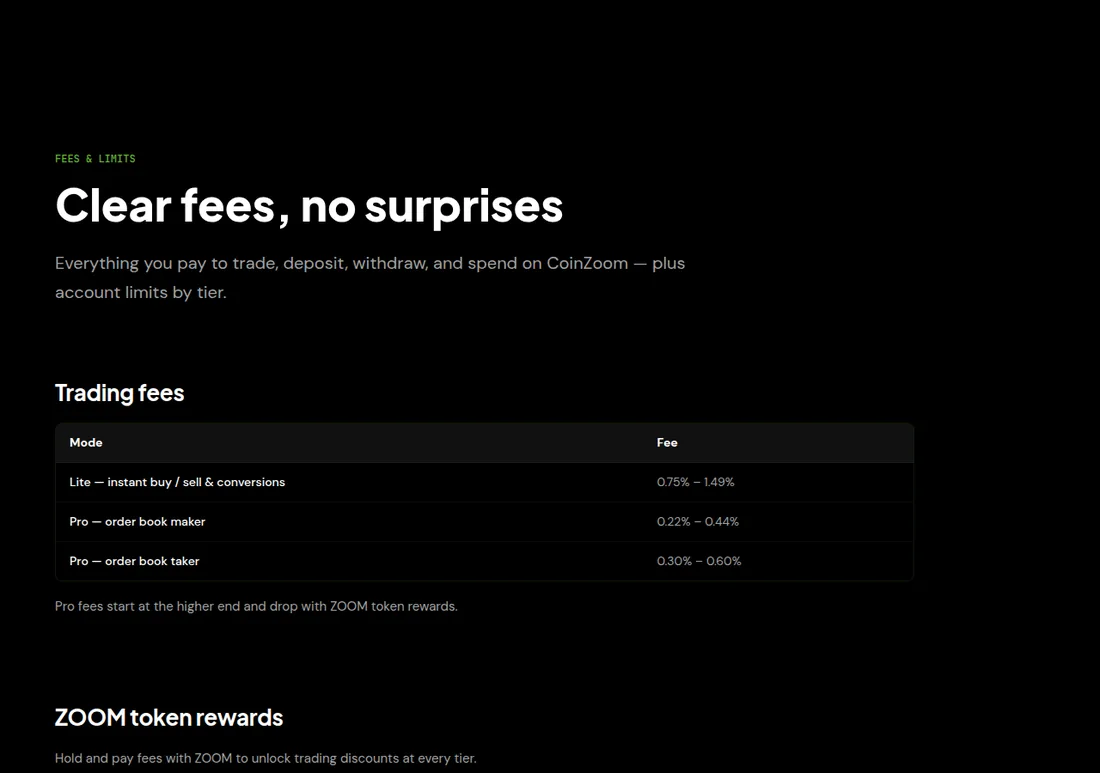
Freedomia spells out the worst case in its own FAQ: processor FX around 2.5%, an additional margin from the payment processor or ATM network of around 3.5-4%, and sometimes a fixed fee charged by the ATM owner - "the total cost can therefore be around 6% in some cases" [6]. CoinZoom sits at the other extreme: "Cash withdrawals (domestic & international) Free" in its published schedule [5].
The math to do before the trip: (provider ATM fee + expected operator fee) ÷ your typical withdrawal. A 2% fee plus a $3 operator fee on a $100 withdrawal is 5%. On a $400 withdrawal it is 2.75%. Fewer, larger withdrawals are usually cheaper - up to the card's daily limit.
Worked example: a 400-euro purchase, priced end to end
Take a mid-market rate of 1.1225 (ECB reference for 2 Oct 2026 [11]) and a USD card. The same 400 EUR purchase on three documented cards:
| Card | Explicit FX | Where the rest hides | Statement (approx.) |
|---|---|---|---|
| Goblin physical | 0% [9] | network rate (Visa margin, unprinted) | ~$449-450 |
| Freedomia | 2.5% [6] | network rate | ~$460 |
| Fold | $3.00 flat [10] | network rate | ~$452 |
The table's lesson: a percentage scales with the purchase, a flat fee does not. The 400-euro restaurant bill and the 4-euro coffee cost the same Fold surcharge - 0.7% vs 67% of the transaction. Match the card to the purchase size, not to the headline.
Two documented nuances worth knowing before you compare. First, form factors can differ: Goblin's physical card converts at 0% own-FX while its virtual card carries a 1% markup inside the rate - included in a roughly 1.5% total difference from Google-type reference rates, not charged on top [9]. The same product, two cost sheets. Second, the deposit leg is a separate cost from the FX leg: a card that spends "free" can still charge 3.5% every time you top it up. Our hidden spreads guide prices that leg; the table above deliberately shows only the spending side.
The DCC trap
At the terminal or ATM abroad, the machine offers: "Charge in USD (your home currency)?" - at a rate worse than the network rate. Documented DCC markups reach 18% [1]. Always choose the local currency: your card's conversion (network rate plus its documented fee) is almost always cheaper than the terminal's offer, and the terminal rate is locked in instantly - there is no post-hoc dispute path.
Some ATMs pre-select DCC. Decline and retry; if the machine won't offer local currency, find another machine. EU Regulation 924/2009 obliges payment service providers to disclose conversion charges as a percentage over the ECB reference rate - a disclosure rule, not a cap [2].
Practical travel checklist
- Test the card at home first - a declined card abroad is a real problem.
- Load before you travel - on-chain funding from a hotel Wi-Fi is not the time to learn your provider's limits (congestion pricing can stall a small top-up for hours - see the funding guide).
- Know your PIN - US-issued cards sometimes default to signature; European terminals may require PIN.
- Carry a backup card (or cash) - a frozen or blocked card with no fallback is the most common crypto-travel failure.
- Check the provider's country support - some cards decline in sanctioned/restricted countries even if the network works there [4]. Our country checker compares documented coverage.
- Screenshot the emergency-contact path - freezing a card from the app is faster than phone support.
Emergency playbook: the card that stops working
Everything above assumes the card works. Plan for the hour it doesn't:
- Freeze first, debug second. If transactions appear that you don't recognize, freeze in the app first and debug second - a false alarm costs nothing, an unfrozen compromised card costs everything.
- Declines cluster on the first foreign transaction. Many issuers flag a first foreign purchase as risk behavior. If your card declines on day one abroad, contact support before assuming the card is broken - a verification call usually clears it.
- Pre-authorizations eat the balance, not the credit line. Hotel and car-rental holds on a debit product debit real money. A $500 hold on a $600 card balance leaves $100 of spendable funds - budget accordingly.
- Know the reload path offline. Lightning top-ups need the provider's app and connectivity; on-chain top-ups need a wallet and a fee estimate. Both fail differently when roaming data is broken - the funding guide covers the rail trade-offs.
- Document everything for disputes. Merchant receipts, terminal screenshots, timestamps. Crypto-card dispute paths run through the issuer's support process, and the statement export is the evidence base (our tax records guide explains what to keep and why).
Which cards travel best
- 0% FX + network-rate conversion: Bitpanda (EUR area), Xapo (worldwide; $1,000/yr membership applies [4]).
- Free ATM access: CoinZoom's published schedule [5].
- Lightning-funded cards: fast top-ups on the road - but only where the provider's app works [6].
What to skip
- Cash advances framed as "purchase" by some providers - they can still carry cash-advance fees. Coinbase One Card and Crypto.com both charge the greater of $10 or 5% per cash advance, with APRs above 32% [7][8]. Check the fee schedule's wording.
- Airline/hotel pre-authorizations on crypto cards: holds can take days to release on some programs, tying up your balance - plan the budget with the holds in mind.
FAQ
Should I withdraw cash abroad with a bitcoin card?
Only after checking both fee layers - the card's ATM fee and the local ATM owner's fee. Freedomia, for example, warns the total can reach ~6% (processor FX ~2.5% plus ATM network margin 3.5-4% plus fixed fees), while CoinZoom advertises free withdrawals and Xapo gives $100/month free.
How bad is Dynamic Currency Conversion really?
DCC markups run from a few percent to as much as 18% over the normal rate, per documented cases. It is always worse than letting your issuer convert at the network rate. Decline every time.
What happens if I accept the terminal's home-currency offer?
The merchant (or its DCC provider) converts the amount at a marked-up rate before the transaction ever reaches your card network. The worse rate is locked in at the terminal and cannot be disputed later.
Do crypto cards work everywhere Visa and Mastercard work?
No. Some issuers block or decline transactions in sanctioned or restricted countries even when the network itself works there. Check the provider's country support before relying on the card abroad.
Is withdrawing with a credit card the same as with a debit card?
No - crypto credit cards route cash advances through credit terms. Coinbase One Card and Crypto.com card charge the greater of $10 or 5% per cash advance, plus APRs of around 32% from day one.
What should I set up before the trip?
Test the card at home, load before you travel, know your PIN, carry a backup card or cash, and bookmark the in-app freeze path. A declined card abroad with no fallback is the most common crypto-travel failure.
Sources
- Wikipedia - Dynamic currency conversion, markups documented up to 18% - accessed 2026-10-05
- EU Regulation 924/2009 (EUR-Lex) - currency conversion disclosure rules - accessed 2026-10-05
- Bitpanda Card - 0% FX with explicit Visa mark-up caveat - accessed 2026-10-05
- Xapo Bank FAQ - 0% FX, ATM ladder ($100/mo free then 2%), $2,000 daily limit - accessed 2026-10-05
- CoinZoom fee schedule - free domestic and international cash withdrawals - accessed 2026-10-05
- Freedomia Help Center - ATM total-cost wording (~2.5% + 3.5-4% + fixed) - accessed 2026-10-05
- Coinbase One Card cardholder agreement (Cardless) - cash advance $10 or 5% - accessed 2026-10-05
- Crypto.com card rate and fee summary (Comenity) - cash advance $10 or 5%, APR - accessed 2026-10-05
- Goblin Cards FAQ - physical card 0% FX, virtual card 1% markup inside the rate - accessed 2026-10-05
- Fold terms and conditions - international transaction fee $3.00 per transaction - accessed 2026-10-05
- ECB euro foreign exchange reference rates - USD/EUR 1.1225 on 2 Oct 2026 - accessed 2026-10-05